Allowing Pets in Rental Properties: A Guide for Landlords...
The Renters’ Rights Act 2025 has introduced significant legal changes and new landlord responsibilities, including how landlords must res...

Property investors can generate a high income from renting out buy-to-let properties but there are some factors to take into consideration before deciding whether it is the best investment option, and whether it is the right time for buying a second property to let.
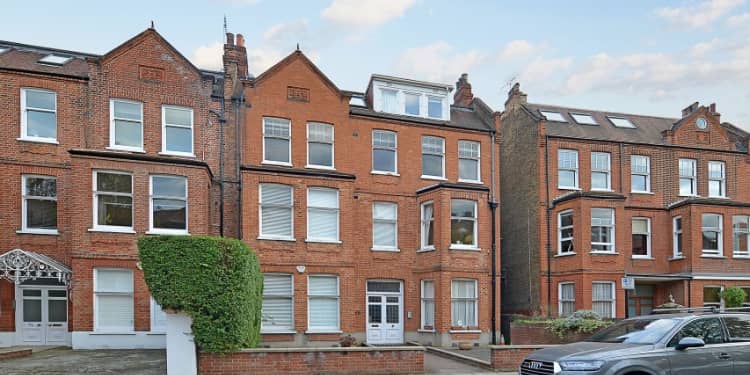
The current property market and interest rates will have a significant impact on the success of your investment, particularly in the short-term. Successful property investors are able to make both short-term and long-term profits, but a good understanding of the market and an effective strategy are both essential.
Changes to landlord tax relief and stamp duty surcharges for second homes have been introduced in recent years, while higher interest rates can be another off-putting factor for landlords. However, there are still lucrative property investment opportunities for savvy investors.
In London, rents inflation was 10.1% in the 12 months leading up to May 2024, with a high demand for property in areas such as Regents Park and Marylebone in central London driving average rent prices up.
Despite changes to landlord tax relief and second property surcharges, property investment can be highly profitable. Compared to alternative investment options such as stocks and shares, property investment is regarded as a lower risk investment. While fluctuations in average house prices do happen, over longer periods, the property market maintains a strong performance.
In addition to delivering regular rental income, investing in a second home can generate long term capital growth, with house prices generally showing excellent growth over 10 or 15-year periods. For example, in January 2010 the average house price in the City of London was £464,436, increasing to £798,179 in January 2024.
Buying an additional property in sought after areas enables investors to build a passive income, and capital growth through increased property value can provide a comfortable financial position and for some investors, the opportunity for early retirement.
Identifying the right type of property to meet your financial objectives involves thorough research and planning. If you already have experience with certain types of properties, your knowledge will provide you with an advantage.
There are several different types of rental property options to consider:
Want to find out more? Explore our articles on how to increase rental income, find out about how to become a landlord in Central London and learn about buy to let guide for Central London.
Once you have decided which type of property to buy, you will need to choose a location that will attract the type of tenants you are looking for. If you decide to rent property to students, the ideal location will be close to universities.
It is better to buy property in areas that you are already familiar with, as you will understand more about the local property market, local amenities, demographics of residents and quality of schools and transport links.
When deciding on an area to buy property, you should research the house prices and achievable annual rental income to calculate your projected rental yield. To work out the rental yield, you divide your annual rental income by the value of the property and multiply by 100. A rental yield of 5% and over is considered to be a good amount.
These are the costs involved in buying a second property:
If you rent out property, you are liable for paying income tax on any profits. The amount you pay will depend on which income tax band you are in and how much profit you make from rent after expenses are deducted. Landlords get a 20% tax credit on second home mortgage interest.
You will also pay stamp duty rates, plus a second home surcharge. If you sell your rental property, you will usually need to pay capital gains tax.
To let out property, you will need to follow these steps:
If you are thinking of buying a second property to let in the Marylebone, Baker Street, Fitzrovia, Regent’s Park, or Maida Vale areas, we will be able to help you find a property to suit your requirements. Contact us today.
The Renters’ Rights Act 2025 has introduced significant legal changes and new landlord responsibilities, including how landlords must res...

The Renters’ Rights Act is the biggest reform to London’s private rental sector for decades. Among the changes Marylebone, Soho...

Your circumstances have changed and you want to rent out your house – but you have a residential mortgage. What are your options? If you ...


